
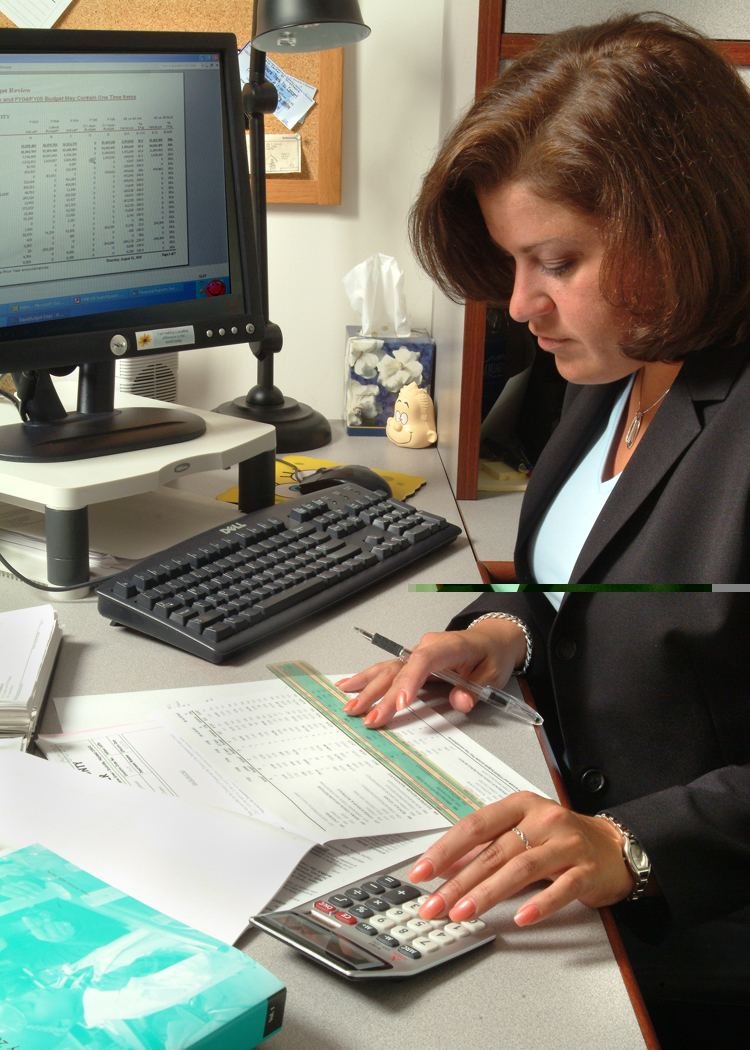
Separating business and personal money is one of the simplest steps a small business owner can take to understand cash flow clearly throughout the year. A dedicated account makes tax records easier to prepare, shows exactly what the business earns and spends, and prevents everyday personal purchases from hiding problems until they become serious. Accountants say the habit also looks more professional to lenders and suppliers, who can see organised records when credit or payment terms are discussed with the owner.
What the Evidence Shows
Owners are advised to pay themselves a regular amount, set aside a percentage of income for tax and review the accounts briefly every week rather than only at year end. Simple bookkeeping software can categorise spending automatically, but the owner still needs to check the figures and keep invoices and receipts safely stored. With cleaner accounts, decisions about prices, hiring and investment rest on real numbers instead of guesswork, giving small firms a firmer base for steady growth ahead. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following small business separate accounts cash flow say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by small business separate accounts cash flow are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with small business separate accounts cash flow will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
